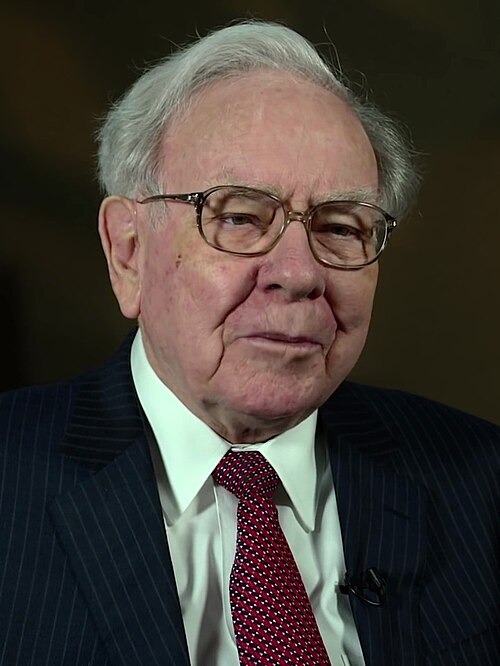
Warren Buffett
워런 버핏
Longtime leader of Berkshire Hathaway who practiced long-term compounding by investing within his circle of competence in businesses with durable economic moats and margins of safety.
1,409 records in all
- Principles 389
- Episodes 279
- Quotes 741
3 free questions a day, no sign-up.
Photo: USA International Trade Administration Public domain Original cropped
Quotes
111 basic records of 741
Quotes are word for word from the source.
Value Investing
Whether we're talking about socks or stocks, I like buying quality merchandise when it is marked down.
Our noteHigh quality assets should be purchased when they are undervalued and offered at a discount.
Circle of Competence
Charlie and I avoid businesses whose futures we can't evaluate, no matter how exciting their products may be.
Our noteAvoid investing in businesses with unpredictable futures regardless of how exciting their products are.
Long Term Investors
We make no attempt to woo Wall Street. Investors who buy and sell based upon media or analyst commentary are not for us.
Our noteFocus on long term investors rather than those who trade based on media or analyst commentary.
Management Autonomy
We tend to let our many subsidiaries operate on their own, without our supervising and monitoring them to any degree.
Our noteTrust subsidiary managers completely and allow them to operate with full autonomy without micromanagement.
Danger of Imitation
"The other guy is doing it so we must as well" spells trouble in any business, but none more so than insurance.
Our noteBlindly copying competitors simply because they are doing it is a dangerous strategy in any business.
Transparent Communication
Our goal, which we pursue both through these annual letters and by our meeting discussions, is to give you a better understanding of the business that you own.
Our noteManagement should communicate transparently to help shareholders fully understand the business they own.
Value of Reputation
We can afford to lose money - even a lot of money. But we can't afford to lose reputation - even a shred of reputation.
Our noteFinancial losses are acceptable but losing even a fraction of the company reputation is intolerable.
Trusting Management
Each of you does a first-class job of running your operation with your own individual style and you don't need me to help.
Our noteTrust capable leaders to run their operations in their own style without unnecessary interference.
Succession Planning
Please summarize the strengths and weaknesses of your primary candidate as well as any possible alternates you may wish to include.
Our noteSuccession planning requires a thorough and objective analysis of the strengths and weaknesses of primary and alternate candidates.
Preferring Wonderful Businesses
At Berkshire we much prefer owning a non-controlling but substantial portion of a wonderful business to owning 100% of a so-so business.
Our noteIt is far better to own a significant minority stake in an outstanding business than to fully own a mediocre one.
Liquidity Management
Charlie and I believe in operating with many redundant layers of liquidity, and we avoid any sort of obligation that could drain our cash in a material way.
Our noteMaintain abundant liquidity and avoid obligations that could severely deplete cash reserves.
Valuation
As I've long told you, Berkshire's intrinsic value far exceeds its book value. Moreover, the difference has widened considerably in recent years.
Our noteA company's true intrinsic value can significantly exceed its accounting book value.
Capital Allocation
At Berkshire, we much prefer owning a non-controlling but substantial portion of a wonderful company to owning 100% of a so-so business;
Our noteOwning a portion of an exceptional business is better than fully owning a mediocre one.
Long-term Focus
Games are won by players who focus on the playing field - not by those whose eyes are glued to the scoreboard.
Our noteFocus on the underlying business operations rather than constantly watching stock price movements.
Circle of Competence
It's vital, however, that we recognize the perimeter of our "circle of competence" and stay well inside of it.
Our noteIt is crucial to identify the boundaries of your expertise and strictly operate within them.
Business and Investing
I've mentioned in the past that my experience in business helps me as an investor and that my investment experience has made me a better businessman.
Our noteBusiness operations and investing experiences mutually reinforce and improve one another.
Speculation
Consciously paying more for a stock than its calculated value - in the hope that it can soon be sold for a still-higher price - should be labeled speculation
Our notePaying more than a business is worth in the hope of selling it higher to someone else is pure speculation.
Fairness and Equality
We do not follow the common practice of talking one-on-one with large institutional investors or analysts
Our noteMaintain fairness by treating all investors equally regarding information access.
Resilience and Strategy
We have intentionally constructed Berkshire in a manner that will allow it to comfortably withstand economic discontinuities, including such extremes as extended market closures.
Our noteBuild a resilient structure capable of withstanding extreme economic shocks.
Compound Interest
The math of repurchases grinds away slowly, but can be powerful over time. The process offers a simple way for investors to own an ever-expanding portion of exceptional businesses.
Our noteConsistent share repurchases serve as a powerful mechanism to increase investor ownership over time.
Investment Strategy
Whatever our form of ownership, our goal is to have meaningful investments in businesses with both durable economic advantages and a first-class CEO.
Our noteThe core goal is to invest in businesses that possess both durable competitive advantages and exceptional leadership.
Share Repurchases
I want to underscore that for Berkshire repurchases to make sense, our shares must offer appropriate value.
Our noteShare repurchases only make sense when the stock is trading at a price that offers appropriate value.
Long-term Investing
The lesson for investors: The weeds wither away in significance as the flowers bloom. Over time, it takes just a few winners to work wonders.
Our noteOver time a few highly successful investments will overshadow the impact of minor failures.
Value Investing
add to it wonderful businesses purchased at fair prices and give up buying fair businesses at wonderful prices.
Our noteIt is far wiser to buy a wonderful business at a fair price than a fair business at a wonderful price.
Equities
I can't remember a period since March 11, 1942 - the date of my first stock purchase - that I have not had a majority of my net worth in equities, U.S.-based equities.
Our noteKeeping the majority of net worth in equities over a lifetime allows one to benefit from long term capital growth.
Accepting Volatility
By accepting the prospect of volatility, we expect to earn higher long-term returns than we would by pursuing predictability.
Our noteHe emphasizes that accepting short-term volatility leads to higher long-term returns.
Business Ownership
The art of investing in public companies successfully is little different from the art of successfully acquiring subsidiaries.
Our noteHe explains that investing in public stocks requires the same mindset as acquiring entire businesses.
Scale and Returns
Our rate of progress in both investments and operations is certain to fall in the future. For anyone deploying capital, nothing recedes like success.
Our noteHe explains that maintaining high rates of return becomes increasingly difficult as capital size grows.
Insurance Pricing
A pernicious aspect of catastrophe insurance, however, makes it likely that mispricing, even of a severe variety, will not be discovered for a very long time.
Our noteHe points out that mispricing in catastrophe insurance can remain hidden for a very long time.
Business Criteria
Both businesses fully meet our criteria: They are understandable; possess excellent economics; and are run by outstanding people.
Our noteInvest in understandable businesses with excellent economics and outstanding management.
You are seeing 211 basic records. Membership answers from all 1,409 of this master's records.
See membershipMore masters in this field
See the whole fieldInvesting and capital allocation
These records are our compilation of public statements and sources. We are not affiliated with or endorsed by Warren Buffett or any related company. If something should come down, tell us. Takedown request form